
Short answer
A first-time buyer of a new Kelowna condo can combine several programs: the federal GST rebate (all 5% GST back on a new home up to $1,000,000), a BC property transfer tax exemption, tax-free savings in a First Home Savings Account, up to $60,000 from RRSPs under the Home Buyers' Plan, and a 30-year insured mortgage. The minimum down payment is 5% of the first $500,000 and 10% of the rest.
This guide is for you if
- You have not owned the home you lived in, or not for several years, and want to buy in Kelowna.
- You are deciding between a new condo and a resale, and want to know what a new home changes.
- You want to understand the programs before you talk to a lender.
On this page
Who counts as a first-time buyer
Each program has its own definition, so check them one at a time. A buyer can qualify for one and not another.
| Program | Who qualifies | What it is worth |
|---|---|---|
| Federal first-time GST rebate | 18 or older, Canadian citizen or permanent resident, and no home you or your spouse owned and lived in this year or the previous four | Up to $50,000; full on a new home up to $1,000,000 |
| BC newly built home exemption | Canadian citizen or permanent resident who moves in within 92 days (not limited to first-time buyers) | No transfer tax on a new home up to $1,100,000 |
| BC first time home buyers' program | Never owned a principal residence anywhere, plus a year of BC residence or two BC tax returns in six years | Up to $8,000 on a home up to $835,000 |
| First Home Savings Account | First-time buyer under the FHSA's own four-year test | $8,000 of room in the first year, $40,000 lifetime |
| Home Buyers' Plan | First-time buyer under the HBP's rules | Up to $60,000 from your RRSPs |
GST on a new home, and getting it back
First-time buyers of a new home may recover the full 5% GST, up to $50,000, on a home priced at $1,000,000 or less, with a reduced rebate up to $1,500,000. The purchase agreement has to be signed on or after March 20, 2025 and before 2031, and you must not have lived in a home you or your spouse owned in that calendar year or the four before it.
On a presale, the rebate is tested on the day ownership transfers to you, not the day you sign, so your situation at completion is what counts. You also need to be the first person to live in the home after it is built.
Property transfer tax: two exemptions, pick one
The newly built home exemption removes the tax on a new home worth up to $1,100,000, with a partial exemption up to $1,150,000. You need to be a Canadian citizen or permanent resident, the home must be your principal residence, and you must move in within 92 days of registration and live there for the rest of the first year. It is not limited to first-time buyers.
The first time home buyers' program removes the tax on the first $500,000 of value, an exemption worth up to $8,000, for a home worth up to $835,000, with a smaller exemption up to $860,000. It requires at least a year of BC residence before registration, or two BC tax returns in the last six years.
On a new home, the newly built exemption is usually worth more, because it removes the whole tax up to $1,100,000. On a presale strata home bought at arm's length, the tax is generally based on the total amount you paid, including upgrades and any assignment premium, rather than the value on the day the title registers.
Saving the down payment
A First Home Savings Account gives $8,000 of contribution room in its first year, to a lifetime limit of $40,000. Contributions are generally tax-deductible and a qualifying withdrawal for a first home is tax-free.
The Home Buyers' Plan lets you withdraw up to $60,000 from your RRSPs for a qualifying home. For a first withdrawal made between January 1, 2026 and December 31, 2028, repayment starts in the fifth year after the year of the first withdrawal. You can use the Home Buyers' Plan and an FHSA withdrawal for the same home, as long as you meet the conditions for each.
Down payment and mortgage rules
The minimum down payment is 5% of the first $500,000 and 10% of the portion above it, for homes under $1,500,000. At $1,500,000 or more it is 20%.
Since December 15, 2024, insured mortgages can be amortized over 30 years for all first-time buyers and for all buyers of a newly built home, and the price cap for an insured mortgage is $1,500,000. With less than 20% down, the mortgage must be insured, and the insurance premium is usually added to the loan.
How a presale changes the timeline
BC gives presale buyers seven days to cancel a purchase contract without penalty. The seven days start on the later of the day you sign the contract and the day you give the developer your acknowledgement that you had the chance to read the disclosure statement. Deposits are paid on a schedule set in the contract and held in trust; Serenity's schedule has not been published.
Mortgage approval for a presale is usually finalized near completion, so get pre-qualified early and plan for rates and your finances to change. BCFSA also warns that if the home appraises below your price at completion, the lender may lend less than you planned, leaving a gap you would cover in cash.
Checklist
- Open an FHSA as early as you can, even with a small amount, so the room starts building.
- Check each program's first-time definition against your own history.
- Get pre-qualified to set a realistic price range before you look at plans.
- Estimate GST, transfer tax and the down payment with the closing cost calculator.
- Keep cash aside for legal fees, insurance and a possible appraisal gap at completion.
- Read the disclosure statement's deposit schedule and estimated completion dates before signing.
Where Serenity fits
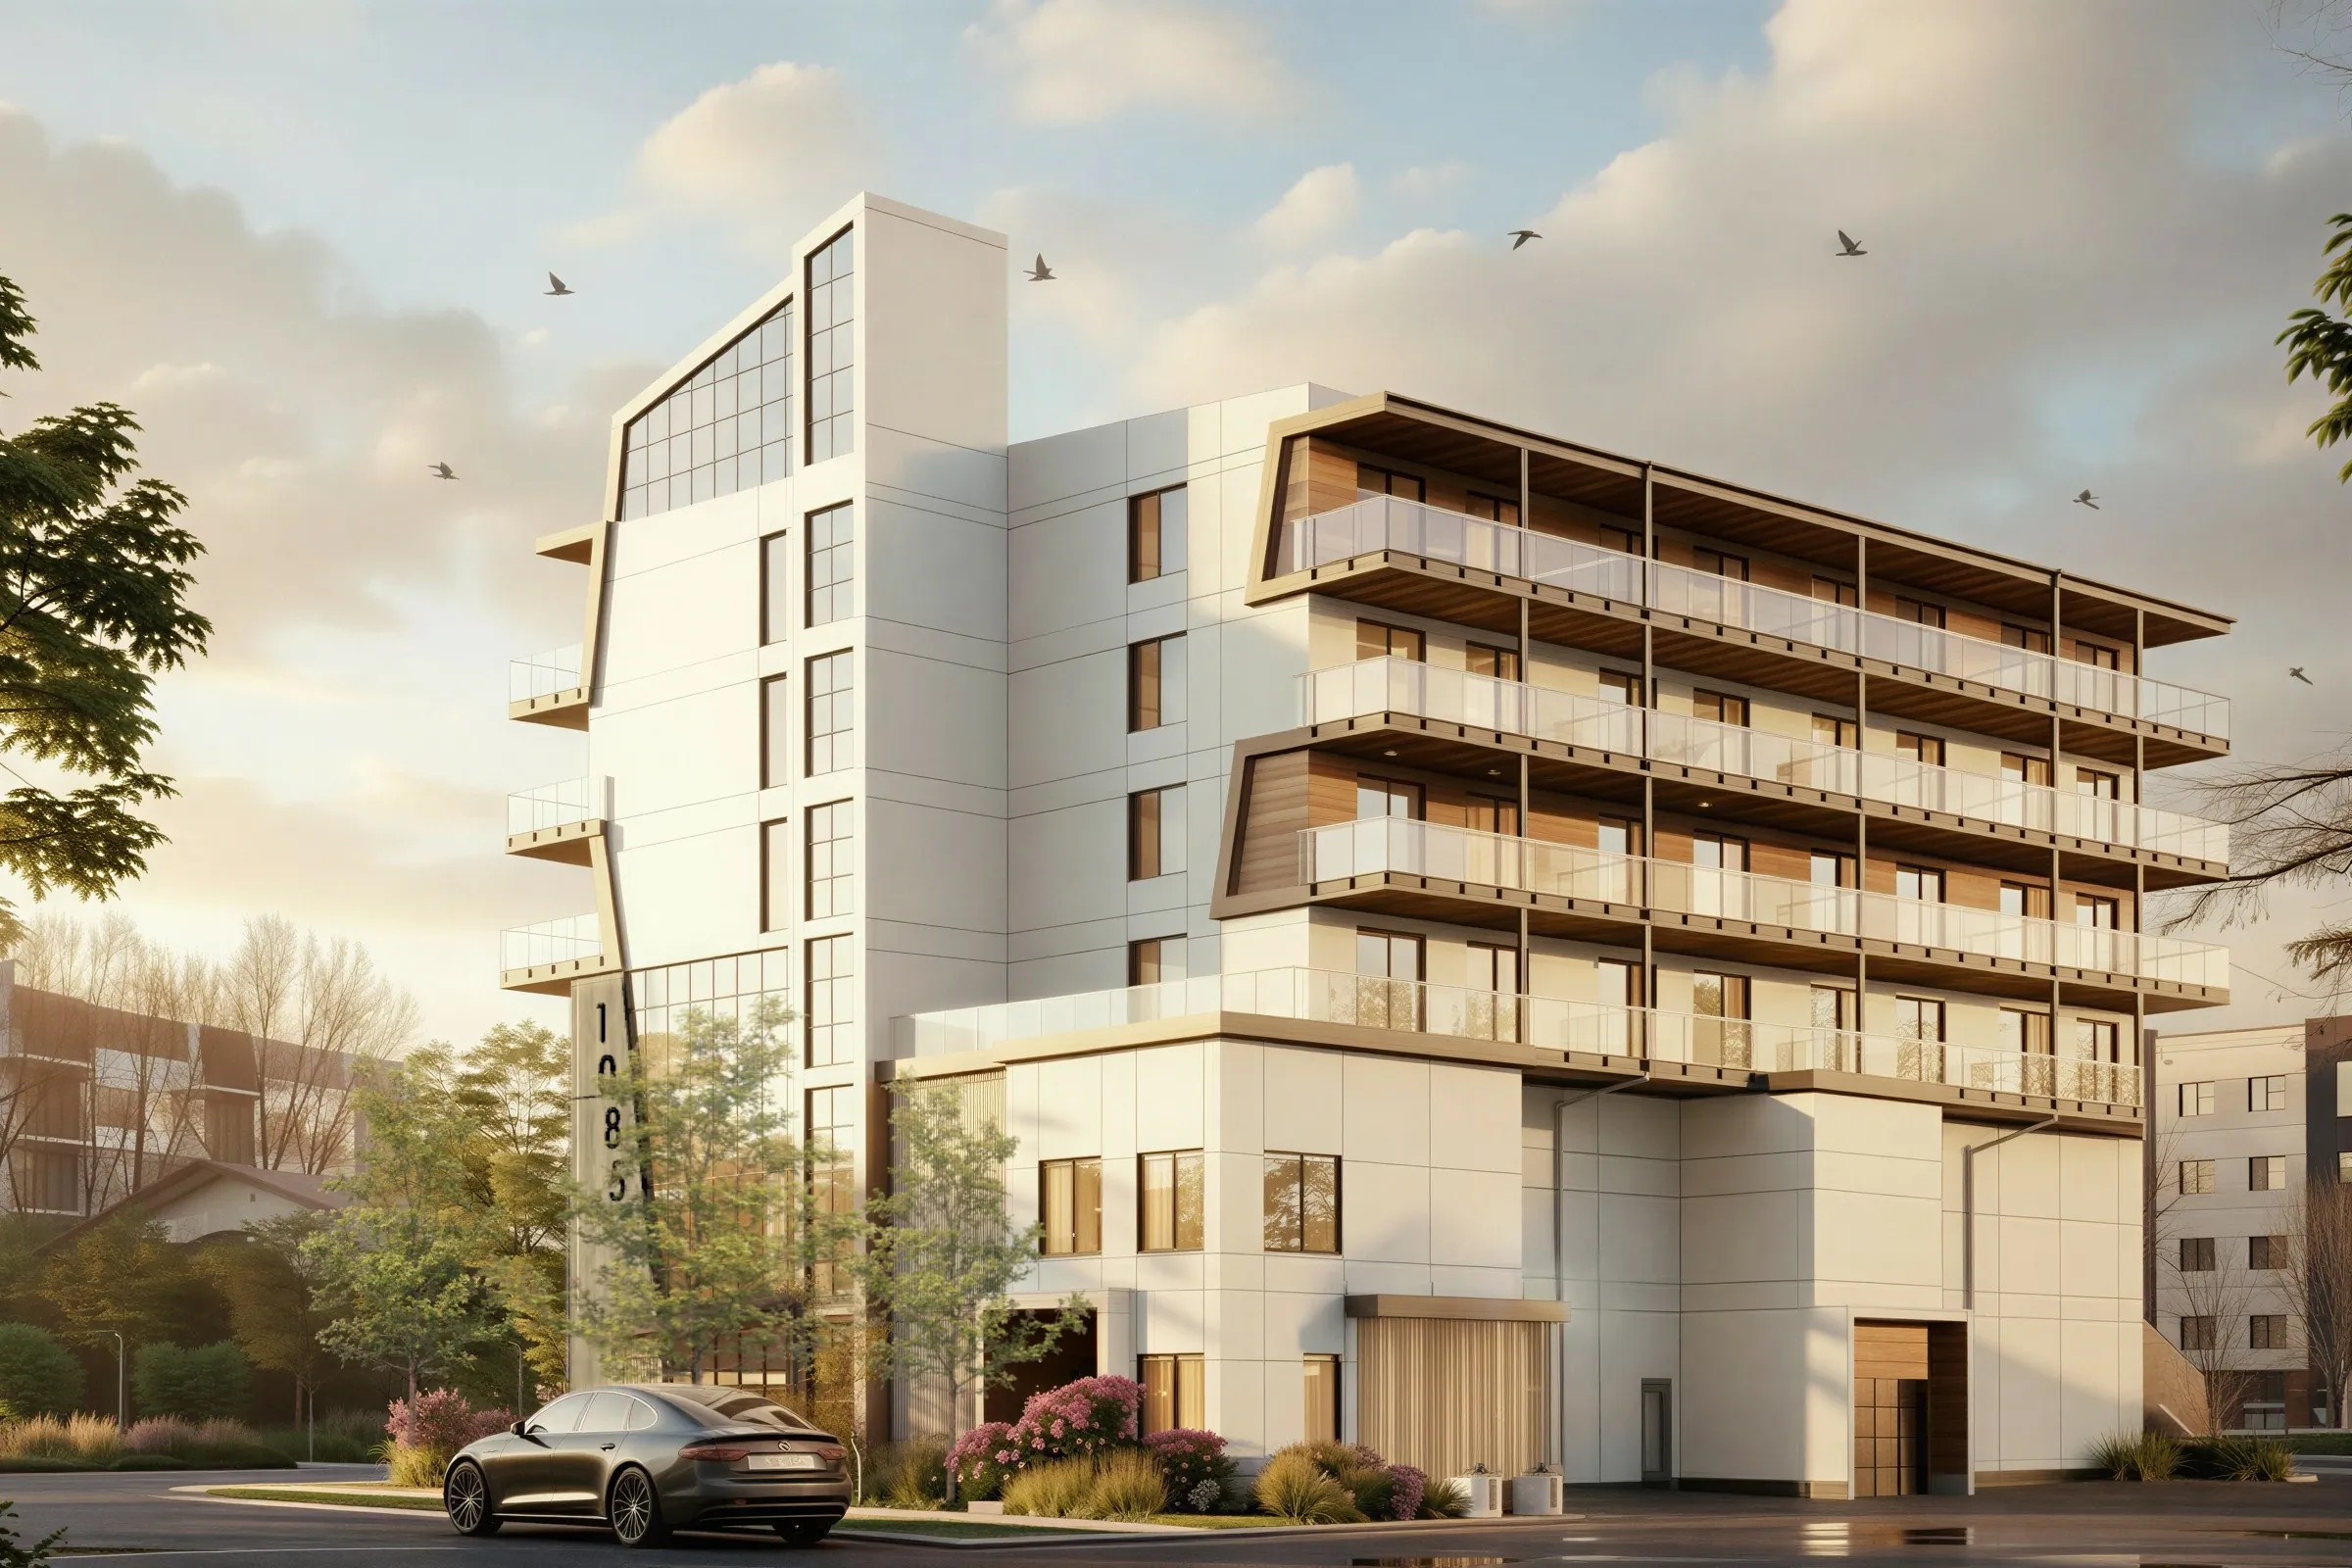
Serenity's most common home is the one-bedroom condo: 16 of its 33 homes are Types D1 and D2, about 660 sq ft each, with a walk-in closet, an ensuite with a double vanity and in-suite laundry. Two-bedroom condos run about 955 to 960 sq ft.
Pricing, deposit schedule, occupancy date and per-plan availability have not been publicly released.
Sources
- 1.Canada Revenue Agency: First-time home buyers' GST/HST rebate (opens in a new tab)canada.ca
- 2.Canada Revenue Agency: Who can apply for the first-time home buyers' GST/HST rebate (opens in a new tab)canada.ca
- 3.Government of BC: Newly built home exemption (opens in a new tab)gov.bc.ca
- 4.Government of BC: First time home buyers' program (opens in a new tab)gov.bc.ca
- 5.Government of BC: Property transfer tax on a pre-sold strata unit (opens in a new tab)gov.bc.ca
- 6.Canada Revenue Agency: First Home Savings Account (FHSA) (opens in a new tab)canada.ca
- 7.Canada Revenue Agency: The Home Buyers' Plan (opens in a new tab)canada.ca
- 8.Financial Consumer Agency of Canada: How much you need for a down payment (opens in a new tab)canada.ca
- 9.Department of Finance Canada: Mortgage reforms in force December 15, 2024 (opens in a new tab)canada.ca
- 10.BCFSA: Consumer Guide to Pre-sale Real Estate Purchases (opens in a new tab)bcfsa.ca
General information read from these sources on October 9, 2026. It is not legal, tax or financial advice; rules change, so confirm your own situation with a lawyer, notary or accountant.